Most real estate investors spend broker calls answering questions. Grant Cardone spends them asking them — and there's a significant difference in what each approach reveals. In a live demonstration, Cardone took a cold call on a 200-unit property near Myrtle Beach, South Carolina, and walked through exactly how he reads a deal, controls a conversation, and identifies in minutes whether something is actually for sale.
Reading the Room Before the Call Even Starts
Before dialing, Cardone looked at the listing details and made an immediate observation: the major institutional brokers — CBRE, JLL, Newmark — weren't involved. Instead, the listing was held by a smaller operator who described the owner as a personal friend.
That one detail told him almost everything. When the large players pass on a listing, it usually means they already know the deal isn't a genuine sale. The listing is being shopped, often because the ownership group is fractured, underwater, or simply testing the market without real conviction to close.
"This is a deal being trolled," Cardone explained afterward. "The four partners probably hate each other right now. Two want out, two don't want to sell because they'll lose everything."
The Live Broker Call: What Actually Happened
 04:45
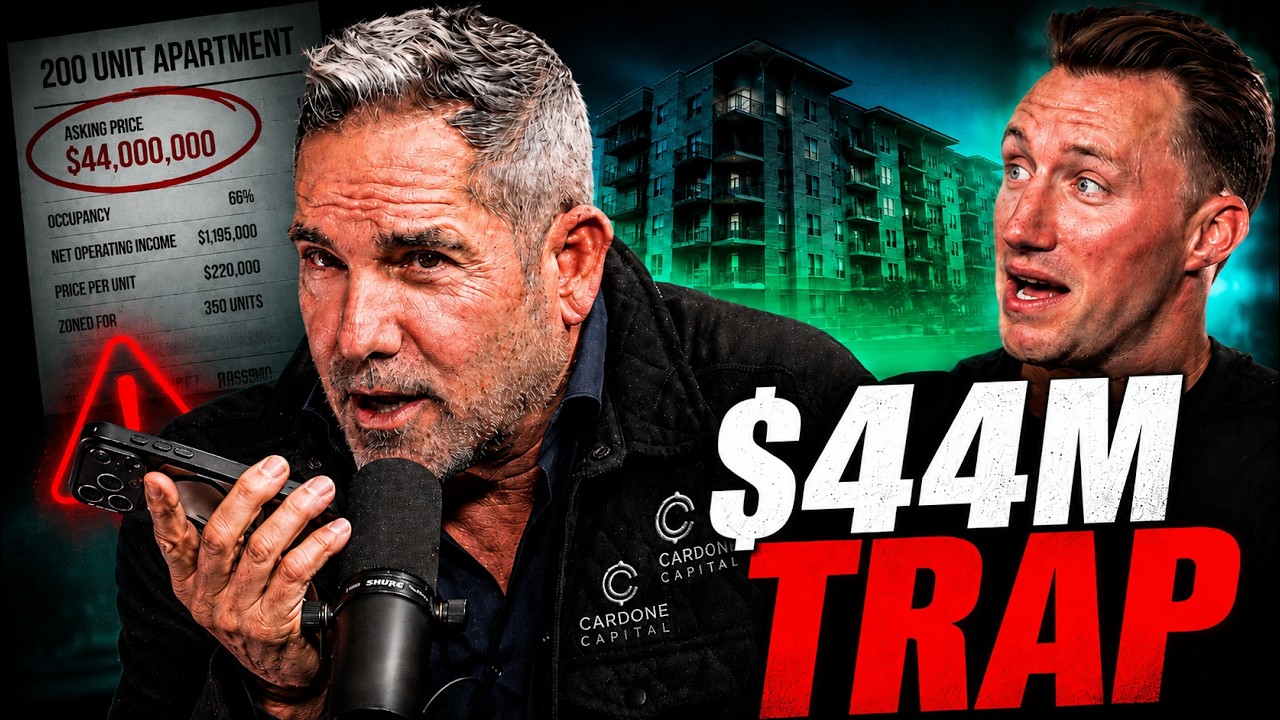
Grant Cardone on a live phone call with the listing broker for a 200-unit Myrtle Beach multifamily property
Watch at 04:45 →
The property: 200 units, zoned for 350, currently 65% occupied, with an existing loan of approximately $26 million. The seller's ask was $44 million — roughly $200,000 per door. The broker mentioned the owner might stay in as a limited partner if the price worked.
Cardone's opening move was to establish credibility and intent immediately: he told the broker he'd been trying to take a position in the Myrtle Beach market for four years, had toured it multiple times with institutional partners, and knew the area well. This wasn't small talk. It was a calculated preemption.
"He no longer needs to validate my net worth, my ability, my finances," Cardone noted. "He asked me zero questions the entire call."
That's the benchmark. If a broker is asking you questions, you've lost control of the conversation. Cardone never let that happen. He interrupted deliberately, filled silences with his own framing, and kept the broker responding rather than probing.
Running the Numbers in Real Time
Cardone worked through the financials out loud during the call itself — a move that serves dual purposes. It demonstrates competence and simultaneously tests the broker's reactions to reality-check the seller's expectations.
- Rents: $1,500 for one-bedrooms, $1,800 for two-bedrooms, $2,250 for three-bedrooms — blended average roughly $1,800
- Gross potential income: $1,800 × 200 units × 12 months = approximately $4.3 million annually
- NOI: The broker confirmed income around $1.5 million, expenses consuming most of it — leaving an NOI Cardone estimated near $700,000
- Debt serviceability: At $700K NOI, conventional lenders would finance roughly $10–12 million against this asset — nowhere near the $44 million ask, or even the $26 million existing loan
The math exposed the problem plainly: the deal is over-leveraged relative to its current income, occupancy is weak at 65%, and the additional 150-unit development pad the broker floated as upside is, in Cardone's view, at least seven years away from penciling.
"The only number I'd buy this at is $36 million," Cardone said after hanging up. "That's $180,000 a door at $1,800 rents. But they're not selling there — they'd lose $8 million. So they're going to wait, jerk you around, and hope the Fed does something."
Why Asking Questions Controls the Conversation
After the call, Cardone broke down what he described as deliberate "deal mogging" — a term for the conversational dominance that keeps the other party perpetually on their back foot.
Every interruption was intentional. Every question was sequenced. The goal wasn't to be aggressive — it was to prevent the broker from ever gaining enough footing to turn the interrogation around. Cardone asked about:
- How the broker got the listing (revealing the lack of institutional interest)
- Why the seller was selling now (exposing motivation and urgency, or lack thereof)
- Current NOI and rents (stress-testing the valuation)
- The seller's walk-away number (anchoring price expectations)
- Whether he had anything better in the market (signaling optionality)
None of these questions are exotic. What's notable is the rhythm — the questions come before the broker can ask any of his own, and each answer feeds directly into the next question. The broker ends the call having revealed everything about his client's position while learning almost nothing about Cardone's.
The Core Lesson: Not Every Listing Is a Deal
The broader takeaway from this exercise isn't a negotiation trick — it's a diagnostic framework. Cardone's first filter is always: who has the listing, and why them? Institutional brokers have deal flow and reputation to protect. They don't take listings they can't close. When a deal circulates outside those channels, the question isn't whether you can get it at the ask — it's whether the ownership structure will ever actually allow a sale to happen.
In this case, four partners, meaningful equity erosion, a refinancing deadline, and a seller who "might stay in as an LP" all point to a group that hasn't fully decided to sell. They're running the market, not exiting it.
At some number — probably around the existing debt — this becomes an acquisition worth considering. But Cardone's judgment is that the sellers aren't emotionally or financially ready to get there yet. The deal exists. The transaction doesn't. Knowing the difference before you spend months in due diligence is what separates experienced operators from everyone else.